Rate Your Relationship with Your Money in 2026Tuesday, November 3, 2026
|
||
|
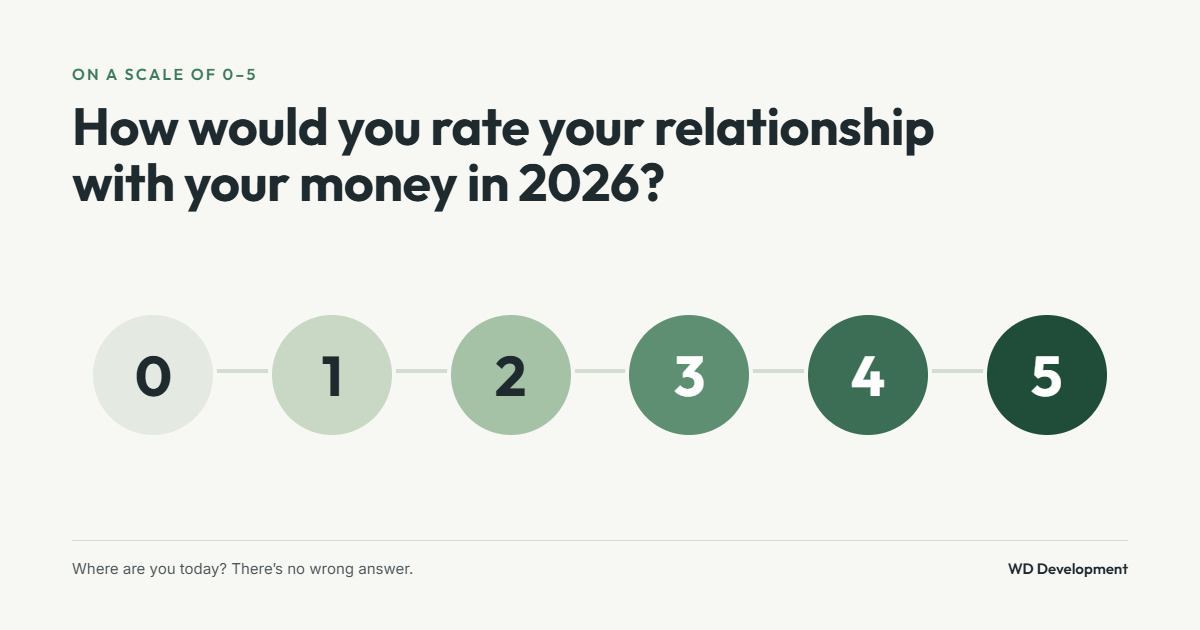
On a scale of 0-5, how would you rate your relationship with your money so far in 2026?
0-1:You can land here for all kinds of reasons. If you’re here, in my experience, best to get yourself up that scale asap. This is the zone that frustration and confusion can either damage your financial stability or cause you to miss opportunities. You need to interact with your money. Anger, frustration and confusion interfere with that.
2-3 :You feel comfortable about some areas, and frustrated or confused about others. If you scored yourself in here, you’ve likely tried to get control of your money a number of times, and feel like you’ve failed. Common comments I hear at this rating: “I’m not making progress towards my goals”; “I feel stuck” or “I’m just treading water”. “I make good money, and I still don’t think I can afford a vacation / the car I want / the housing I want” This zone can also be risky to your financial stability. Too long here and you will book the vacation, buy the car, get the housing (whatever that means to you) despite the cost stretching you and pushing other priorities aside. Or, you are making progress, you could reach your goals and you do that thing you want to do that feels out of reach.
4 :You and your money work well day to day. Most areas are fine, you think. You have goals that you haven’t met yet, but they feel possible. You’re uncertain about whether you’re really okay; maybe the next decision or purchase puts you into the ‘not okay’ category. It’s working, but you’re not sure why. You burn some energy wondering whether you’re really okay now and what future is possible. The most common sense here is : “I have stuff. I don’t know what my stuff can do for me.”
5 :You can also land here for all kinds of reasons. A ‘5’ can mean that you tackled a big financial obstacle this year, and made progress. Paying down debt is the only way to get to no debt- ranking the journey in 2026 as a 5 means that you’ve picked the right paydown strategy for you and your situation, you have the information you need about all of the important financial areas and you’ve been able to make confident choices in 2026. A 5 can mean that you have high financial security, you’re doing all the things that are important to you and you have clarity on your future options. This is about your relationship with your money, not your net worth, income or spending patterns. You can know that you aren’t where you want to be: frustrated at a job loss; relationship breakup; or an unexpected expense that wiped out your carefully built savings account and still be at a ‘5’ with your money relationship in 2026.
If you and your money are in the 0-4 range, what can you do to move up the scale?
What if you’re at a 5?
Be excited, out loud. Financial stress affects other areas of our lives- our relationships, our work performance and our health. When you’ve reduced or eliminated finances from your stress list, that deserves acknowledgement. Do I still need planning when I’m a 5? In my opinion, that’s up to you. Pop in for the next post on how I talk to my clients who chose 5.
|
||
|
||
|
||
|
|
|
|
Sara McCullough 99 November 3, 2026 |